By Costanza Genoese Zerbi, Broker Associate, Costanza Genoese Zerbi & Associates at eXp Realty
Three Closings, One Day: What Three Completely Different Long Beach Deals Taught Me
Today I closed three transactions in Long Beach. On paper, that's just a busy Tuesday. In practice, it was a reminder of how different "sold" can look from one property to the next — and why the details matter so much in this market.
Here's the breakdown, and what each one means for buyers and sellers navigating Long Beach real estate right now.
930 E 1st St: The Own Your Own Nobody Wanted to Touch — Except the Right Buyer
This one-bedroom Own Your Own in a fantastic Long Beach location had everything going for it except a parking space and eligibility for conventional financing. OYOs are structured differently than condos — buyers hold shares in a corporation and a proprietary lease rather than a deed — and that distinction closes off standard mortgage products for a lot of buyers before they even understand why.
We didn't treat the financing gap as a dead end. We found the buyer and the lending path that actually fit this building, and got it closed.
If you're shopping in Long Beach and keep seeing "condo" listings that are actually OYOs, it's worth understanding the difference before you fall in love with a unit. I wrote a full breakdown here: Condo vs. Own Your Own in Long Beach: What Buyers Need to Know.
375 Atlantic Ave: Closing a Deal With a Disclosed Engineering Report
This transaction came with a real complication: an engineering report on file recommending limited occupancy due to a structural concern. That's the kind of disclosure that can end a deal fast if it isn't handled with full transparency on both sides.
We disclosed it clearly, made sure the buyer understood exactly what they were stepping into, and structured the deal around that reality instead of around wishful thinking. It closed — because the buyer had the full picture and could make an informed decision, not despite the report but with it fully on the table.
This is also a good moment to flag: California's condo and HOA financing landscape has been tightening in 2026, and reports like this one are increasingly relevant to whether a building even qualifies for conventional financing. I covered the broader lending shift here: Fannie Mae Condo Lending Changes 2026.
3737 E 2nd St: My Own Deal, and the Hardest One to Let Go Of
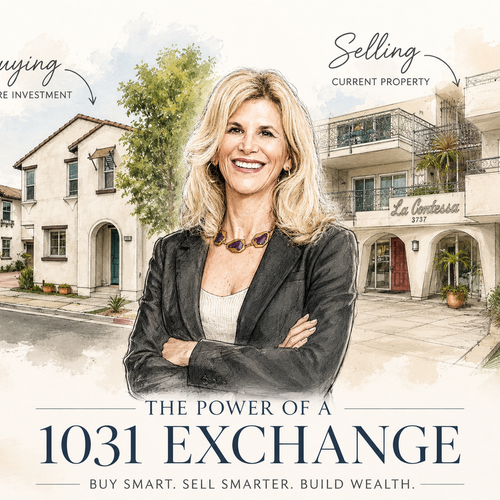
The third closing was personal. This was my parents' home, purchased back in 2000, and selling it was the down-leg of my own 1031 exchange into a new property in Oceanside. I've done hundreds of closings for clients, but doing my own — with the added complexity of exchange timing, boot avoidance, and matching loan proceeds precisely — gave me a fresh appreciation for what I ask my clients to trust me with every time.
I wrote about the full experience, start to finish, here: Selling My Parents' Long Beach Home: What I Learned Doing My Own 1031 Exchange.
The Common Thread
Three deals, three completely different obstacles — a financing structure that rules out most buyers, a structural disclosure that could have killed the deal, and the emotional weight of selling a family home. None of them closed by accident. They closed because every detail got handled instead of glossed over.
That's the same standard I bring to every Long Beach, South Bay, and Orange County transaction, whether it's a $400K starter unit or a multi-million dollar sale.
FAQ
What is an Own Your Own (OYO) property in Long Beach? An OYO is a stock cooperative — buyers own shares in a corporation that holds title to the building, plus a proprietary lease giving them the right to occupy their unit. It's not the same as owning a deeded condo, and it significantly narrows available financing.
Does an engineering report on a building always kill financing or a sale? Not necessarily, but it has to be disclosed and understood by the buyer. Depending on the finding, it can affect whether a building qualifies for conventional financing under current Fannie Mae and Freddie Mac guidelines.
How does a 1031 exchange work when you're selling your own primary or family-owned property? The mechanics are the same as any 1031 exchange — same-taxpayer rule, timelines, and a Qualified Intermediary are all still required — but the process still requires the same discipline around avoiding "boot" and matching proceeds to the replacement property.
Thinking About Buying or Selling in Long Beach?
Whether your deal is straightforward or complicated by financing quirks, disclosures, or an exchange, I'd rather walk you through it before you're under contract than after. Get in touch and let's talk through your specific situation.
Read next: Selling My Parents' Long Beach Home: What I Learned Doing My Own 1031 Exchange
Check out this article next